
野火损失攀升,商业保险公司会拒绝为公用事业承保吗?
2023年美国多地野火造成巨额损失,Xcel Energy和Hawaiian Electric等公用事业公司面临严峻诉讼压力。保险公司对野火风险的承保态度正在分化:部分退出市场,部分探索创新产品。专家对市场前景看法不一,政府介入与自保模式成为讨论焦点。
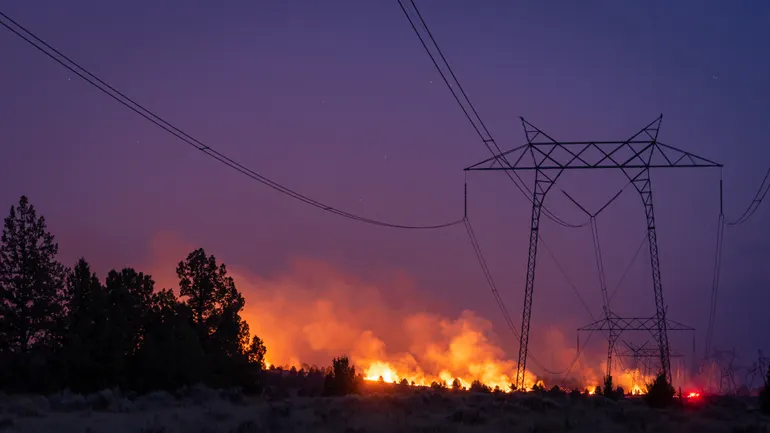
In 2023, the United States once again faced costly wildfires in multiple regions. In June, an investigation into the 2021 Marshall Fire—recognized as the most destructive wildfire in Colorado's history—revealed that hundreds of litigants were lining up to sue Xcel Energy, as a fallen transmission line may have ignited part of the fire. Xcel executives disclosed during a July earnings call that the company's potential liability for the fire could exceed its insurance policy limits.
Two months later, Hawaiian Electric stated in a filing with the U.S. Securities and Exchange Commission (SEC) that, as part of "prudent scenario planning," the company was "seeking advice from various experts" to address litigation related to the wildfires that devastated Maui in August. The company has not declared bankruptcy, but it has held discussions with restructuring advisors, hired a new chief financial officer with experience in utility bankruptcies, and injected $75 million into a fund for victims willing to waive their lawsuits.
Utility bankruptcies due to wildfire-related litigation are not without precedent—Pacific Gas and Electric Company (PG&E) is a typical example. But bankruptcy is not the only consequence of the rising wave of wildfire lawsuits. Paul Doherty, a PG&E spokesperson, said insurers are also reconsidering how—and in some cases whether—to provide liability coverage to utilities located in high wildfire-risk areas.
"At PG&E, we have experienced different reactions from insurers in the commercial market," Doherty said in an email. "These range from some insurers choosing to no longer offer wildfire liability coverage, to sub-limits for wildfire-related losses, to higher deductibles and rising premium costs for underwriting wildfire risk."
Insurance analysts say that the rising risk of severe wildfires due to climate change, along with changes in the legal environment—which increasingly hold utilities responsible for losses caused by these fires—has indeed altered the pricing logic of utility liability insurance policies. But regarding long-term impacts, analysts are divided. Some analysts believe that the growing demand for wildfire-related liability insurance will spur innovation, giving rise to new insurance products entering the market.
However, other analysts argue that government intervention may be necessary to practically maintain electricity supply in certain parts of the United States.
"I cannot assert whether insurance will be available, or whether utilities will encounter underwriting issues," said Rade Musulin, principal at Finity Consulting. "But what I can say is that many of the prerequisites for an insurance market that provides stable and affordable prices are not being met in this area."
Climate risk, or climate uncertainty?
Musulin said that for insurance to function, actuaries need to be able to do two things: calculate the losses associated with a potential event, and then calculate the likelihood of that event occurring. This enables them to estimate the cost for an insurer to underwrite a specific risk—and to estimate the premiums that would cover those potential costs.
In most cases, actuaries incorporate historical data when estimating potential risks and losses, Musulin said. And this is precisely the problem insurers face when underwriting modern threats such as terrorism, cyberattacks, and climate change—historical data does not represent today's risk environment.
Regarding wildfires and climate change, Musulin said the insurance industry is relatively confident in its understanding of the scientific issues. They have most of the information they need about how the frequency of droughts and strong winds is changing, and how these issues lead to more frequent and severe wildfires in the future. What is unknown—and currently causing the greatest anxiety for insurers—is how infrastructure designed for past climate conditions will perform under unprecedented future conditions.
"The scientific evidence is fairly robust. The question is what happens when this climate acts on something. How likely is that thing to be damaged?" Musulin said.
Musulin noted that one cannot simply assume that if wind speeds increase by 10% during a severe storm, the damage caused by the storm will also increase by 10%. He said most structures are designed to withstand extreme conditions up to a certain limit—and beyond that limit, they fail.
"At wind speeds up to 100 miles per hour, there may be almost no damage," he said, "but at 110 miles per hour, buildings collapse."
Musulin said wildfire risk is also influenced by changes in the legal environment. It is not just that our societal expectations around climate and industry responsibility for climate-related disasters like wildfires have changed. In the past, determining who or what ignited a wildfire was relatively difficult. But if there is a camera pointed at a transmission line, it becomes much easier. And today, cameras are everywhere.
Add inflation and rising property values to that, Musulin said, and you begin to raise genuine questions about whether insurance—or anyone—can absorb the costs of losses that may be associated with wildfires in the coming years.
Insurance innovation
Alp Can, an actuary at USI Insurance Services and chair of the Climate Index Working Group that compiles the Actuaries Climate Index, holds a more optimistic view of the future of commercial insurance for utilities. He does not intend to downplay the importance of wildfire liability risks to utilities—the scale of potential liabilities in the billions is hard to underestimate—but Can believes the problem is manageable. More importantly, he and other industry observers believe wildfire risk may spur innovation in the commercial insurance sector, which could ultimately benefit utility companies.
Historically, utility insurance policies have focused more on risks related to power generation, with less attention to transmission.
"This situation needs to change," Can said, "because wildfire risk is not just a function of climate change, but also a function of how utilities manage their transmission lines."
This has prompted actuaries to collaborate with other industry experts to develop models that can set premiums based on factors such as whether a utility has buried its transmission lines, or whether it has plans to prevent vegetation from contacting overhead lines.
"These factors will all be taken into account, and insurers will leverage improvements in catastrophe modeling and location tools, such as satellite spatial monitoring, to precisely assess the level of risk involved for individual assets and locations," Can said.
Can said insurers are also exploring contractual innovations such as parametric insurance. Parametric insurance is contingent coverage based on specific parameters—for example, in the case of wildfires, the total acres burned in a single event. With this type of insurance, if a wildfire reaches a certain catastrophic scale, the policy triggers and covers the utility's liability. Can said wildfires are well-suited for this type of insurance due to their binary nature—the insured property is either not in the path of the event, or it is affected by the wildfire's spread, and in the latter case it is typically burned, constituting a total loss.
"With these tools and methods available, I believe we are capable of addressing this particular risk," Can said. "Insurers will begin to become more prudent about potential losses in the billions, but given all the mitigation measures, I believe underwriting will be feasible."
All of this looks like fairly good news to Mike Doyle, a senior equity analyst at Edward Jones who tracks Xcel Energy. Insurance costs are rising, and insurance is not something you like to see a company spending too much on, Doyle said. But it also creates the financial need for transmission upgrades and grid hardening, which will drive capital requirements and present opportunities for investors.
"A common theme with utilities is that when a problem is identified, they find a solution. And usually that solution costs money," Doyle said. "If regulators deem it important to address the problem, they will invest the capital and earn a return."
Musulin said that by raising the costs utilities incur due to poor grid maintenance, insurers can also help utilities convince regulators and investors of the need for grid hardening. In the long run, he believes this will drive the industry to invest in a future-ready grid, thereby reducing the risk and cost of catastrophic wildfires. In the coming years, the growth of electrification and renewable energy will require large-scale grid investment, which provides an opportunity to address wildfire mitigation at the same time, he said.
But that is the long-term view, Musulin said. Rebuilding the grid takes years, and in the meantime, he said, governments may need to step in in some high wildfire-risk areas to practically maintain electricity supply. Because if utilities face massive liabilities and rising insurance premiums in wildfire events, they may conclude that the most financially prudent solution is to shut down the grid when fire risk is highest—a phenomenon already so common that claims against Hawaiian Electric argue its failure to de-energize the grid is responsible for the losses in Maui.
Similarly, PG&E states on its website that it may implement Public Safety Power Shutoffs under conditions such as low humidity, strong winds, or dry vegetation near transmission lines.
But that is not the only strategy PG&E has adopted in response to rising insurance costs and reduced availability of suitable policies. Doherty said PG&E chose to transition to a 100% self-insurance model in late 2023, seeking a more cost-effective solution for wildfire risk—meaning the company has ceased third-party insurance and plans to use its own funds to cover future wildfire liabilities.
PG&E can also use the California Wildfire Fund, which reimburses participating utilities for legal claims arising from wildfires. The program is funded through surcharges on electricity bills and administered by the California Earthquake Authority—a publicly managed, privately funded insurer created by the state legislature. According to Doherty, PG&E expects these programs to save consumers up to $1.8 billion over the next four years.
Doherty said this public-private partnership approach "is an innovative solution that protects utilities while supporting continued investment in safe, clean, and reliable electricity in California at reasonable consumer costs."
Correction:A previous version of this article mischaracterized Hawaiian Electric's statement in its SEC filing. Regarding the question of whether it had hired restructuring advisors, the company stated in the filing that it was "seeking advice from various experts" as part of "prudent scenario planning."