
KEMA Labs: Quality Will Define the Future of the Power Industry
The energy shock caused by recent events in the Middle East has revealed that the global power supply chain, after the COVID-19 pandemic and the 2022-2023 crises, has no buffer left. KEMA Labs analysis indicates that fuel shortages, rising costs of critical materials, logistics congestion, and project standstills are compounding to create systemic strain. More concerning, accelerated procurement and relaxed qualification standards are leading to a silent decline in equipment quality—many products are failing independent certification tests. In this urgent market environment, rigorous type testing and independent verification have become the last line of defense against quality risks and for maintaining grid resilience.
The recent evolution of the situation in the Middle East is often simplified by outsiders into a familiar story: energy prices soaring once again, global markets hit once more. This interpretation is not wrong, but it is dangerously one-sided. Beneath the visible rise in electricity prices, a deeper and more systemic crisis is spreading along the supply chain of the power industry—an already fragile architecture is being pushed to a breaking point. This is not merely an interruption of energy flows, but a stress test on the infrastructure that supports them, and the existing system does not seem ready to pass it.
A System Long Past Its Safety Margins
Long before this disruption occurred, the buffer capacity in the global power value chain was already nearly exhausted. The aftermath of the COVID-19 pandemic and the crises of 2022-2023 has pushed transformer delivery lead times to over two years, while forcing manufacturers to operate at full or near-full capacity. Inventories are thin, expansion is slow, and supply chains are stretched tight.
Recent events in the Middle East act as a force multiplier—sudden, concentrated, and layered on top of a system already operating beyond its limits. The result is that the entire network has almost no redundancy left, and even minor disruptions can cascade into major delays.
Public discourse has long been focused narrowly on LNG shortages and surging electricity prices. However, the true scope of the impact is far broader and cuts across multiple interconnected dimensions.
Fuel remains the most direct pressure point, with constrained LNG flows directly hitting gas-dependent power systems. But upstream vulnerabilities follow closely: critical materials such as copper, grain-oriented electrical steel, insulating polymers, and transformer oil are all exposed to risk—not necessarily from direct shortages, but from rising costs and fragmented logistics networks.
Meanwhile, manufacturing and transportation are under heavy strain. Longer shipping routes, rising insurance premiums, and increasing port congestion are stretching delivery lead times across the board. The Middle East—a paradox of being both a supplier and a major destination for grid investment—has seen projects stall or even become stranded. And the crisis itself is accelerating electrification trends, further driving up demand for grid infrastructure at the worst possible time.
What emerges is not a temporary imbalance, but a systemic squeeze whose duration may outlast the geopolitical triggers themselves.
The Quiet Erosion of Quality
The most insidious risk may lie not in delays or cost overruns, but in the gradual erosion of quality. Supply shortages often follow a predictable pattern: as lead times lengthen, buyers expand their supplier lists, procurement processes accelerate, and qualification standards are quietly relaxed.
The damage rarely manifests immediately. It often surfaces years later—in the form of transformer failures, degradation of cable systems, and switchgear faults. These are not marginal defects, but failures capable of destabilizing the entire grid.
Evidence from independent testing organizations such as KEMA Labs (the testing, inspection, and certification arm of CESI) paints a troubling picture. A significant proportion of equipment fails initial certification tests, highlighting a persistent gap between nominal compliance and demonstrated performance. In a constrained market, this gap is widening.
Testing: The Last Line of Defense
In stable times, testing is often viewed as a procedural checkpoint. Under current conditions, it is evolving into a critical safeguard. Independent verification—through rigorous type testing—is one of the few mechanisms capable of anchoring quality levels amid mounting pressure.
The logic is clear. Compared to the consequences of failure—blackouts, prolonged repairs, and significant financial losses—the cost of comprehensive testing is almost negligible. Yet, as procurement timelines tighten, the temptation to cut corners is growing.
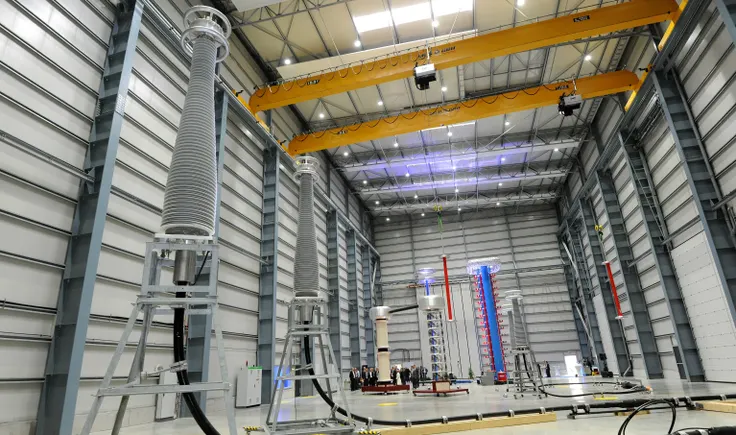
With its global testing infrastructure covering high-power and high-voltage systems, KEMA Labs serves as a technical counterbalance to these pressures. Its certification framework provides an objective reference point in a market increasingly driven by urgency rather than discipline.
A Crisis That Will Not Pass Easily
In this increasingly constrained landscape, the role of independent verification bodies such as KEMA Labs is becoming harder to ignore: they are not guarantors of safety, but mechanisms capable of revealing the widening gap between nominal compliance and actual performance.
The lesson is unsettling, yet clear. The resilience of the power industry does not depend solely on capacity or investment. It depends on the ability to maintain quality under pressure—a challenge the industry is currently only partially equipped to meet, and one that even the most rigorous testing frameworks can only partially mitigate if broader market discipline continues to erode.