
Scope 3 Emissions Retention Becomes Focus: The Final Direction of SEC Climate Disclosure Rules
The SEC's climate disclosure rules proposed in March 2022 have sparked widespread controversy due to requiring companies to disclose Scope 3 emissions. The rule was originally scheduled for release in October 2023 but has been postponed to April 2024. Opponents argue that Scope 3 disclosure requirements are overly burdensome and exceed the SEC's authority, while supporters point out their alignment with EU and California regulations. Experts predict that Scope 3 provisions may be removed, but even if removed, Scope 1 and Scope 2 could still face legal challenges.
In March 2022, the U.S. Securities and Exchange Commission (SEC) proposed climate disclosure rules requiring companies to describe their greenhouse gas emission levels and strategies to mitigate climate risks in Form 10-K. The proposal immediately drew strong criticism from some Republican lawmakers, industry groups, and dozens of state attorneys general.
At the heart of the controversy is the disclosure requirement for Scope 3 emissions—emissions not directly produced by the company but by entities in its value chain or supply chain (as defined by the U.S. Environmental Protection Agency). Although companies do not directly produce these emissions, Scope 3 often accounts for the majority of their total greenhouse gas emissions.
Since the rule proposal was published, the SEC has received more than 16,000 public comments, leading the agency to repeatedly delay the release of the final rule, most recently missing the expected October 2023 target date. Last month, the SEC revealed plans to finalize the rule by April 2024, but did not specify whether the final version would include revisions to the Scope 3 disclosure requirements.
Given the strong opposition, experts and some companies doubt whether the Scope 3 requirement will ultimately survive.
Why has Scope 3 sparked such controversy?
The SEC's initial proposal required companies to disclose Scope 3 emissions if they are material or if the registrant has set greenhouse gas reduction targets that include Scope 3. The SEC stated that such disclosures would help investors assess companies' exposure to and management of climate-related risks, particularly transition risks, but small reporting companies would be exempt.
The proposal is not far removed from existing global disclosure requirements, such as the EU's Corporate Sustainability Reporting Directive (which has broader Scope 3 requirements) and California's climate disclosure laws (which also mandate Scope 3 reporting). However, this has not shielded it from criticism. Opponents argue that the requirement imposes an excessive burden on companies, requiring disclosure of information that is not material to investor decisions and exceeding the SEC's congressional mandate.
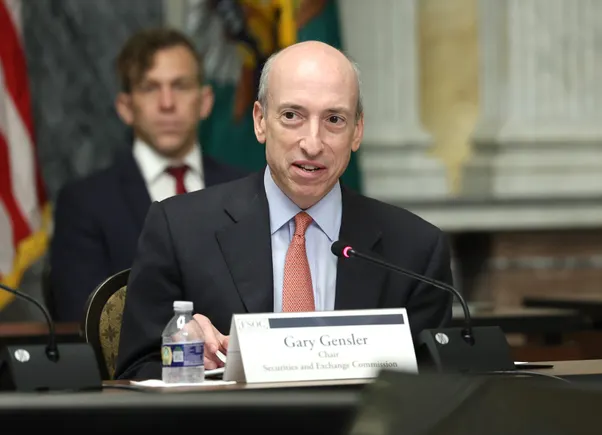
In June 2021, organizations such as the Western Energy Alliance and the American Petroleum Institute wrote to SEC Chair Gary Gensler, asking whether the SEC has congressional authority to regulate in the climate disclosure space and what consequences might arise if it attempted to aggressively regulate in that area. The letter stated: "Compared to mature financial disclosures, climate and ESG reporting is still in its infancy, and it would be better to let competitive systems continue to develop rather than have the federal government impose bureaucratic constraints." The letter also asked the SEC not to exceed its investor protection and capital formation responsibilities.
In June 2022, Texas Attorney General Ken Paxton, along with 12 other attorneys general, co-signed a letter opposing the rule. Paxton called the climate rule "flawed," particularly the Scope 3 emissions disclosure requirement, because it "cannot provide investors with consistent and reliable information." He noted that Scope 3 reporting requires companies to "collect information from a wide range of sources, including data on transportation, distribution, processing, use, and end-of-life treatment of products," and that the accuracy of such data may be low. He wrote: "The reliability of Scope 3 greenhouse gas emission reporting is also questionable, which could make statements including Scope 3 potentially harmful to the investors the SEC is supposed to protect."
After receiving a large volume of such feedback, the SEC stated it would seek to avoid exceeding its authority when finalizing the climate risk rules. Gensler told the U.S. Chamber of Commerce in October 2023: "We did receive a lot of feedback that these estimates could lead companies to request forms and figures from their supply chains, etc. So, the staff is looking at how we can ensure we don't indirectly do what we cannot do directly—we do not regulate private companies."
Next Steps: The Fate of Scope 3
Although some companies oppose any form of climate disclosure requirements, many believe the SEC's proposal aligns with existing disclosure rules in the EU and domestically in the U.S., such as California's Senate Bills 253 and 261.
Renee Morin, Chief Sustainability Officer at eBay, told ESG Dive: "For eBay, we have no qualms about disclosing emissions because we have been doing it all along. I think the real issue is that there are multiple lines of work globally and domestically." However, Morin noted that eBay, along with companies like Amazon, Facebook, Salesforce, and Intel that already voluntarily disclose climate information, provided feedback to the SEC on what works and what does not, particularly around Scope 3 emissions reporting.
These companies wrote in a June 2021 letter: "Given that climate disclosures rely on estimates and assumptions that involve inherent uncertainties, it is important not to subject companies to undue liability, including liability from private parties. Additionally, reporting deadlines should allow sufficient time for companies to collect and verify information obtained from third parties."
The lengthy finalization process has left some companies uncertain whether the Scope 3 disclosure requirement will survive in the SEC's climate disclosure rule. Mark Stach, Chief Services Officer at Sphera (a provider of ESG performance and risk management software, data, and consulting services), told ESG Dive: "At this point, it is uncertain whether reporting on companies' indirect emissions from suppliers (i.e., Scope 3) will be included in the final rule. I don't think it's a done deal yet."
Erin Martin, a partner at ESG and sustainability consulting firm Morgan Lewis, echoed a similar prediction, telling ESG Dive that experts generally believe Scope 3 is "likely to be cut." Martin, who worked in the SEC's Division of Corporation Finance for over a decade, said Scope 3 remains "one of the major areas of concern in implementing the necessary policies and procedures to provide such disclosures." She also noted a lack of sufficient external infrastructure to record and provide high-quality data about companies' value chains. However, she added that even if Scope 3 is excluded from the final rule, legal challenges are unlikely to be avoided. Martin said: "Even if Scope 3 no longer appears in the final rule... I think there will still be significant opposition to Scope 1 and Scope 2."