
Are tariffs good or bad for the U.S. energy storage industry? Experts say it's complicated
The Trump administration's aggressive tariff policies have troubled the booming U.S. energy storage industry, with stock analysts turning cautious on import-dependent original equipment manufacturers and project developers delaying investment decisions. Experts say that without clarity on long-term import tariffs, industry challenges may deepen over the next two years before global supply chains rebalance.
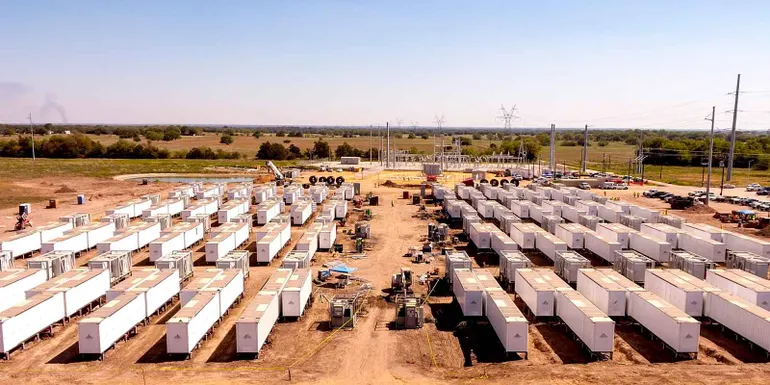
U.S. President Donald Trump's confrontational and chaotic trade policies have begun to weigh on the country's booming energy storage industry—stock analysts are turning cautious on original equipment manufacturers (OEMs) that rely on imports, and project developers are delaying investment decisions. Analysts and industry insiders say that without clearer signals on long-term import tariffs, the challenges facing the industry could deepen over the next year or two, until global supply chains rebalance.
"We are in a world that is very different from last month," said Ravi Manghani, senior director of strategic sourcing at Anza Renewables.
The most significant impact of the "Liberation Day" tariffs may be a sharp reduction in commercial energy storage development in key markets such as Texas—even though Trump has rolled back the tariffs for most countries, he has maintained three-digit rates on Chinese imports. Manghani noted that developers with signed offtake agreements can renegotiate prices with customers, but commercial developers planning to start construction in 2025 may simply wait until next year, hoping the issue is resolved by then. In his observation, this is already happening.
Despite short-term turmoil and global supply chain requirements that force even most U.S.-based manufacturers to source inputs from overseas, energy storage industry insiders told Utility Dive they remain optimistic about the industry's prospects. Some expect protectionist policies to boost U.S. battery manufacturing in the long run and potentially open space for alternatives to lithium-ion technology.
"We are watching a movie we have never seen before"
According to data from the Peterson Institute for International Economics, the average U.S. tariff on Chinese imports is now 124.1%, six times higher than at the start of Trump's second term.
Bloomberg NEF energy storage analyst Isshu Kikuma said this rate is enough to push the deployment cost of a four-hour lithium-ion battery energy storage system in the U.S. above 2023 levels.
"We have not yet updated our installation forecasts, but we expect a significant drop in near-term annual additions, especially after 2025, due to higher-than-expected costs and policy uncertainty," Kikuma said.
Although some stationary storage developers have accelerated construction in 2025 to come online before the existing 17.5% Section 301 tariff increase next year, "many projects in the pipeline will be severely affected," putting longer-duration developers into a "wait-and-see" mode, he added.
Manghani noted that the willingness of battery supply chain companies to absorb import tariffs has largely disappeared, forcing buyers to make tough choices: absorb costs themselves, delay deliveries until prices are expected to fall, or attempt to renegotiate offtake agreements to reflect higher energy storage system costs.
Whether offtakers are willing to cooperate is another matter. Manghani said that in a rapidly changing environment, both parties may prefer to delay projects by months rather than renegotiate terms. Developers and customers had similar precedents during the pandemic-induced supply chain crisis—when electrical equipment prices rose and lead times extended—but the scale of this tariff shock is unprecedented.
"We are watching a movie we have never seen before," Manghani said.
Planning for stationary storage projects typically takes 12 to 18 months, so projects with fixed supply contracts already signed for 2025 delivery were likely negotiated last year, and their bottom lines may not be significantly impacted, said Kelcy Pegler, CEO of FlexGen. But if current uncertainty persists, that will change.
"Signing contracts in a tariff environment of over 100% is very difficult," Pegler said. His company, which provides "OEM-agnostic" energy management systems, is already working with customers to find alternative sourcing options.
For commercial developers with tight timelines and no offtake agreements to renegotiate, project economics "could be completely overwhelmed," which could freeze activity for this group, which accounts for 25% to 30% of the U.S. stationary storage market, Manghani said. This would disproportionately hit the Electric Reliability Council of Texas (ERCOT) territory, where commercial projects are concentrated.
A freeze in ERCOT storage activity could amplify the potential impact of a series of fossil-fuel-friendly, anti-renewable bills in the Texas legislature this spring. For example, S.B. 388 would require that for every new megawatt of wind or solar capacity added, one new megawatt of "dispatchable" generation (excluding batteries) be added.
Planning amid uncertainty
Trump calls tariffs key to revitalizing U.S. manufacturing, but experts expect companies across industries to delay large-scale reshoring plans amid ongoing uncertainty.
The generous 45X manufacturing tax credits in the Inflation Reduction Act have driven billions of dollars in U.S. battery supply chain investment, especially in downstream segments like cell and module assembly.
But according to Evelina Stoikou, senior energy analyst and head of battery technology and supply chain at Bloomberg NEF, U.S. lithium-ion battery cell factories take up to three years to build, so much of the capacity announced since the IRA passed in August 2022 has not yet come online. Moreover, the U.S. has very little capacity for inputs like anode and cathode active materials—which Stoikou says are the most expensive components of battery cells.
So, while persistent protectionist policies may push U.S. storage buyers to seek U.S.-assembled batteries, tariffs on key inputs mean these locally produced alternatives will also be more expensive, Stoikou said.
The U.S. does have abundant raw materials for lithium-ion batteries, including vast lithium deposits in inland Southern California, and potentially even richer formations in the south-central U.S.—which ExxonMobil plans to mine later this decade. Canada also has abundant mineral resources, making it particularly well-suited to be a future "upstream powerhouse," Manghani said.
But because mining and processing are complex, capital-intensive businesses with payback periods spanning decades, they require a degree of long-term certainty that simply does not exist right now, he added. The result: the latest tariffs are unlikely to spur mining investments that have not already started.
This raises the question: can tariffs boost existing U.S. mining operations—one of the government's stated goals? For example, active mines in Wyoming produce tens of millions of tons of soda ash annually, a key precursor for sodium-ion batteries, which advocates hope will eventually outcompete lithium-ion on cost. The U.S. also produces ample iron and phosphorus feedstocks, which can be used in both lithium iron phosphate (LFP) batteries—the preferred chemistry for stationary storage—and sodium-based batteries.
"Domestic supply for the sodium-ion battery industry could be fully met without approving new mines," said Cam Dales, co-founder of U.S. sodium-ion battery startup Peak Energy.
The bottleneck currently lies further downstream in the supply chain.
"While we have all the minerals, we have no midstream processing or component manufacturing capacity, meaning we are currently completely dependent on imports," Dales said.
A coherent U.S. energy security policy should acknowledge China's dominance in lithium-ion batteries and use tariffs to nurture a domestic sodium-ion supply chain—which Dales says could get off the ground by 2030.
"If there were a transitional period with lower tariff rates on materials and components, gradually increasing over several years as domestic supply develops, this tariff system would be perfect for U.S. battery companies," he said.
Who benefits?
Unless and until that happens, Kikuma said U.S. storage buyers will seek to reduce reliance on China and source more from South Korea, Japan, and Southeast Asian countries like Vietnam—which reportedly offered to cut tariffs on U.S. imports to zero shortly after Trump's April 2 tariff announcement.
Manghani added that Indonesia, with its abundant precursor reserves and processing capacity, could eventually become an upstream supplier to U.S. battery makers and buyers; resource-rich countries in the Middle East and Latin America could also play that role.
In the U.S., the biggest beneficiaries of the trade war may be existing manufacturers with idle capacity. This includes Viridi, a small producer in Buffalo that makes modular, "fail-safe" battery systems and claims its risk of thermal runaway is far lower than conventional products.
"We have the ability to scale to nearly gigawatt-hour annual capacity, and committed orders are far below that number, so we can deliver as demand grows," said CEO Jon M. Williams. In April, Viridi announced it had acquired a Northern California production facility from Moxion—a lithium-ion battery supplier that declared bankruptcy last August.
"Tariffs are not all bad; depending on the outcome, they could actually shift the U.S. economy toward renewable energy manufacturing... But I think no honest person can predict the outcome of these policies in 6, 12, or 18 months," he added.