
Harris and Trump Present 'Diametrically Opposed' Policy Impacts on ESG Issues
With the U.S. presidential election approaching on November 5, the differences between Vice President Harris and former President Trump on climate and ESG policies have become a focal point. Experts predict that a Harris administration would be more favorable to the interests of ESG investors, while a Trump administration might adopt a confrontational stance. The composition of Congress, the direction of SEC rules, and the fate of tax credits under the Inflation Reduction Act all face different prospects depending on the election outcome.
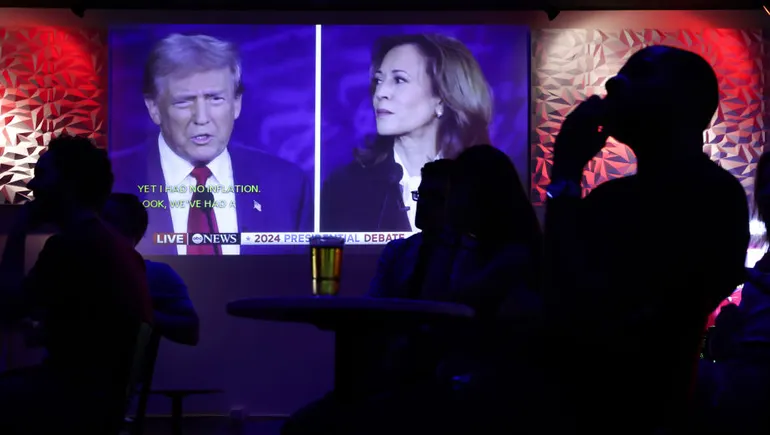
An extraordinary presidential election cycle is nearing its end, with the only certainty being that current President Joe Biden will not seek a second term. Voters will cast their final ballots on Tuesday, November 5, deciding whether Vice President Kamala Harris can shed the "Vice" to succeed her boss, or whether Donald Trump returns to the White House for a second term.
The outcome will also determine how the U.S. addresses issues such as climate, sustainability, and ESG, as Harris and Trump largely represent opposite ends of the spectrum on these matters.
The two presidential candidates share some common ground: both support, to varying degrees, expanding U.S. oil and natural gas production, imposing some form of tariffs on Chinese clean technology products and electric vehicles, and backing nuclear energy infrastructure. Beyond that, they take vastly different paths on climate issues.
"We expect that, depending on which candidate is elected, the issues advocated by ESG investors will be affected in diametrically opposed ways," Tom Kuh, head of ESG strategy at Morningstar Indexes, said in an email comment. "Put most simply, a Harris administration would be more favorable to ESG investor interests, while a Trump administration would be hostile."
However, Aruna Kalyanam, global tax policy leader at EY, noted that regardless of which administration takes office, its ability to act on ESG-related issues—especially legislation—will be constrained by the balance of power between Congress and the White House.
"The composition of Congress is crucial," Kalyanam said in an interview.
Here is an analysis of how a Harris or Trump administration would impact the ESG and sustainability landscape.

Kamala Harris
Harris has a strong record of supporting climate and social justice policies. However, she has not made climate a central pillar of her campaign in an effort to gain broader appeal.
As a California senator, Harris was an early co-sponsor of the original Green New Deal, which aimed to address climate change and invest in renewable energy. Shortly thereafter, she introduced the Climate Equity Act of 2020, which sought to highlight the impact of new environmental legislation or federal investments on low-income and disadvantaged communities. The bill would also have required federal agencies to conduct climate and environmental justice analyses of proposed or final rules that could affect such communities.
As vice president, Harris cast the tie-breaking vote to pass the Inflation Reduction Act, which incentivizes and expands domestic production of clean energy technologies. The law, one of Biden's signature legislative achievements, was signed into effect in August 2022 and includes more than $369 billion in climate and clean energy tax incentives.
What a Harris win would mean for climate and ESG
Despite Harris's deep background on the issue, she has avoided making climate change policy a central pillar of her campaign since securing the Democratic presidential nomination in August 2024. She has mentioned the issue only a few times since then, without providing specific details.
At the Democratic National Convention in August, Harris briefly touched on climate in her wide-ranging speech, highlighting "the freedom to breathe clean air, drink clean water, and be free from the pollution that fuels the climate crisis" when discussing threatened "fundamental freedoms."
Experts view this stance as a strategy to attract a broader swath of American voters, especially moderates who do not hold strong positions on climate change.
"(Her strategy) certainly shows intelligence and savvy because she doesn't yet know where the moderate voter stands on climate change," Julie Anderson, professor and program director of the sustainability management program at American University's Kogod School of Business, told ESG Dive on Thursday.
"She's certainly trying to secure a win... and to win, she needs to appeal to the broadest base of moderate voters," Anderson said.
However, despite Harris's recent caution, environmental advocates, climate experts, and political figures expect that, if elected, she would become an active advocate for climate change and push policies to move the country toward a clean energy transition.
"A Harris administration would seek to develop further regulations to protect communities facing adverse impacts from the accelerating transition, with a focus on creating job security and opportunities in regions traditionally dependent on fossil fuel employment," said David Shepard, energy and utilities expert at management consultancy Baringa.
"(Under Harris,) Democratic policies might also continue to focus on expanding manufacturing capacity to achieve domestic sourcing of key clean technology components, thereby reducing reliance on foreign manufacturers and creating green jobs domestically," he added.
Experts predict Harris would build on the climate progress made during Biden's presidency, including efforts to strengthen voluntary carbon markets, strategies to cut super-pollutant greenhouse gas emissions, and the commitment to halve U.S. greenhouse gas pollution by 2030 from 2005 levels.
Anderson—who spent over three decades in the asset management industry before moving into academia, where she managed BlackRock's sustainable exchange-traded fund suite—said Harris would "to a large extent" continue many of the policies introduced by the Biden-Harris administration, especially the implementation of the Inflation Reduction Act and the expansion of electric vehicle infrastructure and subsidies.
Anderson believes Harris is "playing the long game" on climate policy. She said an administration under the Democratic nominee would continue to work to maintain the U.S. role as an international climate leader and prioritize global cooperation.
Shepard agreed: "Harris has long been an advocate for international cooperation, so she is likely to remain within the Paris Agreement framework and continue funding international decarbonization efforts," he told ESG Dive on Thursday.
Biden rejoined the global climate treaty on his first day in office in January 2021, after Trump formally withdrew in 2020.
The fate of SEC rules
A Harris victory would also safeguard several climate-related regulations whose fate hangs in the balance, especially the U.S. Securities and Exchange Commission's climate risk disclosure rule.
Although the climate rule was finalized in March, it immediately faced multiple legal challenges. The agency paused implementation of the rule in April pending resolution of the litigation.
The final rule requires large companies to disclose climate-related risks that have had or are "reasonably likely to have" a material impact on the company; any mitigation or climate adaptation measures the company has taken "as part of its strategy"; the use of internal carbon pricing, transition plans, or scenario analysis, if any; and processes related to climate risk oversight and management. Investors increasingly demand such information in a standardized, comparable format.
Several other ESG-related rules are on the SEC's agenda, including those involving greenwashing, human capital management, and corporate board diversity—all of which are in the rulemaking process or pending finalization. With only days until the November 5 presidential election, these rules are increasingly likely to extend into the next administration's term.
"A Harris administration would support the proposed SEC corporate climate disclosure rule currently being challenged in court," Kuh said. "Trump would roll back these rules."

Donald Trump
While a Harris administration would have the opportunity to build on Biden-era climate progress, the contours of how a second Trump term would approach ESG issues can be glimpsed from his first-term actions and the Republican-led House over the past two years.
In an August interview with Elon Musk, Trump said climate change or global warming is not the "biggest threat" and claimed it would actually create "more oceanfront property," heightening concerns among climate activists and advocates about the prospect of a second term.
Experts note that a second Trump term could abandon defenses, halt rulemaking, or roll back multiple ESG-related rules from the Labor Department and SEC, and claw back as much as possible of the Inflation Reduction Act's clean energy tax credits.
According to BloombergNEF's energy election outlook, a Trump presidency would negatively impact clean power, transportation, and industrial markets, as well as sustainable finance. If Republicans also control both chambers of Congress, the business outlook for these sectors is expected to be "very negatively" affected. Oil and gas is the only climate-related sector whose business outlook would get a boost under Trump, with a "very positive" impact under unified Republican control.
The anticipated contraction of climate policy under Trump and its consequences would ripple through federally regulated retirement plans, how companies report material risks, and the ecosystem of supporting businesses that have emerged to support sustainability initiatives.
A shift in agency mandates
If Trump returns to the White House, the agencies supporting him would have different goals, and pending ESG-related measures at the Labor Department and SEC could quickly die.
Trump's first term "was not very favorable to many initiatives at the Department of Labor," and ESG was the most scrutinized area, said Josh Lichtenstein, partner at Ropes & Gray LLP, who leads the firm's ERISA and benefits practice.
The Labor Department under the Biden administration is currently defending a rule that allows pension fund managers to consider ESG factors as a tie-breaker. The rule, in effect since January 2023, was designed to counteract the "chilling effect" of a rule implemented by the Labor Department under Trump, the agency said when issuing the 2023 rule.
Lichtenstein said the previous fiduciary rule was worded so broadly that trustees of private 401k plans subject to ERISA worried that even including index funds or target-date funds not focused on sustainability themes could expose plan sponsors to allegations of considering ESG factors in investment decisions.
Lichtenstein expects a Trump administration would seek to return to the 2020 fiduciary rule that chilled pension plan managers. If legal challenges are not finally resolved before the change in administration, a Republican-led government would likely stop defending it in court, and the department could refocus on "pecuniary factors."
"While the rhetoric from a Trump administration on that rule is typically 'this is just protecting retirees,' I think many plan sponsors and industry participants, including asset managers, would view a return to that rule as a fairly significant problem for the normal operation of U.S. retirement plans," he said.
While a reversal in direction on the Labor Department fiduciary rule is expected to cause upheaval and uncertainty, corporate America does not have the same concerns about a Trump-led SEC potentially abandoning its climate risk disclosure rule—which was already facing multiple legal challenges.
The House has been critical of the climate risk disclosure rule crafted by the SEC under Chair Gary Gensler, and House-passed spending bills have included policy riders aimed at repealing the Labor Department's fiduciary rule and the SEC's climate rule. The actions of the (Republican) House over the past two years—including occasionally treating ESG and these two agency rules as "bogeymen"—could provide a template for the next Trump administration's actions on the issue.
However, beyond SEC rules, the EU's own corporate ESG disclosure requirements will apply to U.S. companies starting in 2026, California has enacted its own climate risk disclosure rules, and other states are considering similar measures.
"You have to do it to some extent," Kalyanam said. "Many, many large companies are already looking at this. So it may not be the SEC, but it will affect some market in which you operate."
Can Trump claw back IRA tax credits?
Although Trump has made clear he would seek to withdraw the U.S. from the Paris Agreement again, he has also expressed intent to claw back as much as possible of the Inflation Reduction Act's tax credits. However, a second Trump term might find it not so easy to dismantle his predecessor's signature climate legislation.
While changes in direction at the Labor Department and SEC are largely matters of executive directive and agency authority, any move by Trump to repeal IRA tax credits would require congressional approval, which both Kalyanam and Derek Flakoll, U.S. policy analyst at BloombergNEF, consider unlikely even under a Republican-controlled Congress. Flakoll noted in an email comment that 18 congressional Republicans have publicly opposed repealing the IRA.
A more likely scenario is that a Republican-controlled Congress would seek to phase out tax credits for projects that begin construction after 2026. Flakoll said such a scenario represents the "most severe plausible scenario" for renewable energy markets. BNEF's tax credit repeal scenario—modeling the impact of a 2026 sunset date—would result in a 17% reduction in wind, solar, and storage buildout.
"Politicians are reluctant to disrupt the business environment, making it more realistic to expect that credits would be phased down over several years and/or sunset dates would begin a few years out but earlier than currently expected," Flakoll said in an email comment to ESG Dive.
Flakoll noted that the clean electricity production and investment tax credits currently in the IRA do not phase out until U.S. power sector emissions fall by 75% from 2022 levels. He said in the earliest case, their uninterrupted phaseout date would be in the late 2030s.